
Key points
- Scottish Mortgage halves China exposure to 11% over last six years
- Trust remains highly bullish on select industry leaders including BYD, CATL, and ByteDance
- Local research essential for finding undervalued growth stocks and disruptive business models
Despite high-profile headlines about Scottish Mortgage Investment Trust halving its exposure to China over the past six years, trimming its portfolio allocation from 24% at the end of 2020 to 11% as of September, the trust’s managers say there remain “super-exciting growth companies in China”.
For the Baillie Gifford investment trust, which held total assets of £17.75 billion ($23.55bn) at the end of August and backs both public and private growth companies, the reduction marks a recalibration toward a higher bar for investment rather than an outright retreat. While many global investors have fled the Chinese market amid a sluggish property sector, low consumer confidence, and shifting regulations, Scottish Mortgage remains invested in a concentrated group of the country’s most innovative enterprises.
The decision to pare back overall exposure was primarily driven by China’s domestic regulatory environment and mounting geopolitical tensions, particularly the threat of US restrictions limiting American capital from flowing into Chinese businesses.
“We want to have access to these exceptional companies, but we’re aware that there is a shared common risk between them,” said Tom Slater, manager of the Scottish Mortgage Investment Trust.
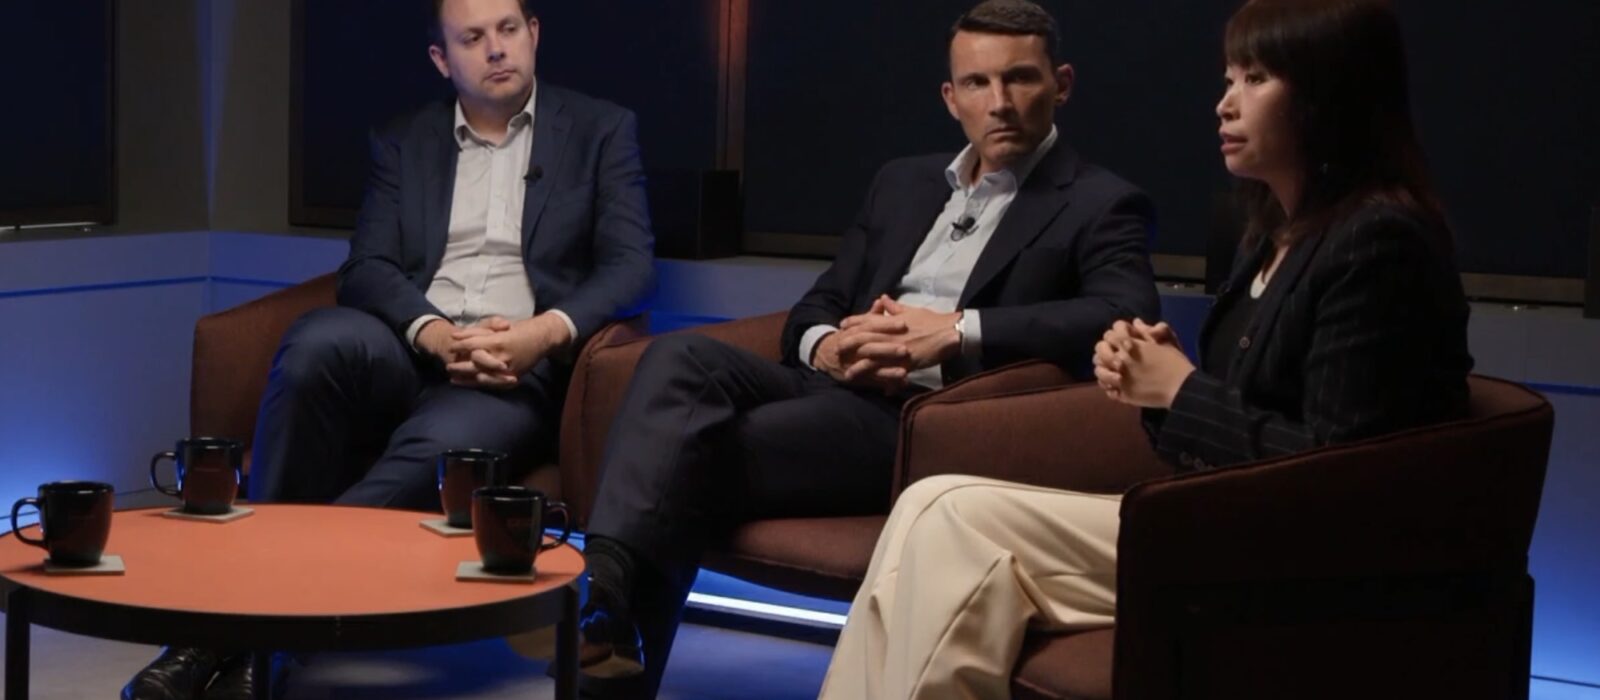
Speaking during the trust’s September digital conference alongside Slater and Linda Lin, head of Baillie Gifford’s China Equities Team, fellow manager Lawrence Burns explained how these headwinds are built into their valuations. He said: “There’s a risk that America tries to limit the amount of American money that can be invested in Chinese companies, and that can have an impact on valuations. So we consider not just the individual risk-reward of the company, but also the collective exposure.”
However, Burns warned that avoiding Chinese stocks entirely does not insulate global portfolios from regional risks, pointing to Western giants like Apple and Tesla. “Just because you don’t own any Chinese companies, it doesn’t mean you don’t have China risk in your portfolio,” Burns noted. “When you’re investing in China, the market is very pessimistic. And you can see that in the very low valuations applied to very fast-growing, capable companies.”
Despite the macroeconomic gloom surrounding China’s property sector and cautious consumers, Lin stressed that remaining invested in China is still critical. Assessing the country solely on headlines, she argued, is “a bit like judging a restaurant from the weather outside, because every time we actually sit down with the founders, we see the situation very differently.”
In areas such as green technology, advanced manufacturing, robotics and even AI, China is not only catching up, it is setting the pace, she said. “The right question to ask every time is can we still find those super-exciting growth companies in China, even through a very difficult economic situation. I think that is the reason why stock picking matters in the game,” Lin added.
Scottish Mortgage said it is still bullish on Chinese tech and automotive stocks including BYD, CATL, and ByteDance.
Recounting a visit to BYD’s headquarters, Burns dismissed the view that Chinese electric vehicles (EVs) lack sophistication as “wrong – out of date”. “Both Linda and I visited BYD, and that was not the impression we’d had for many years and was definitely not the impression we got on that visit,” he said.
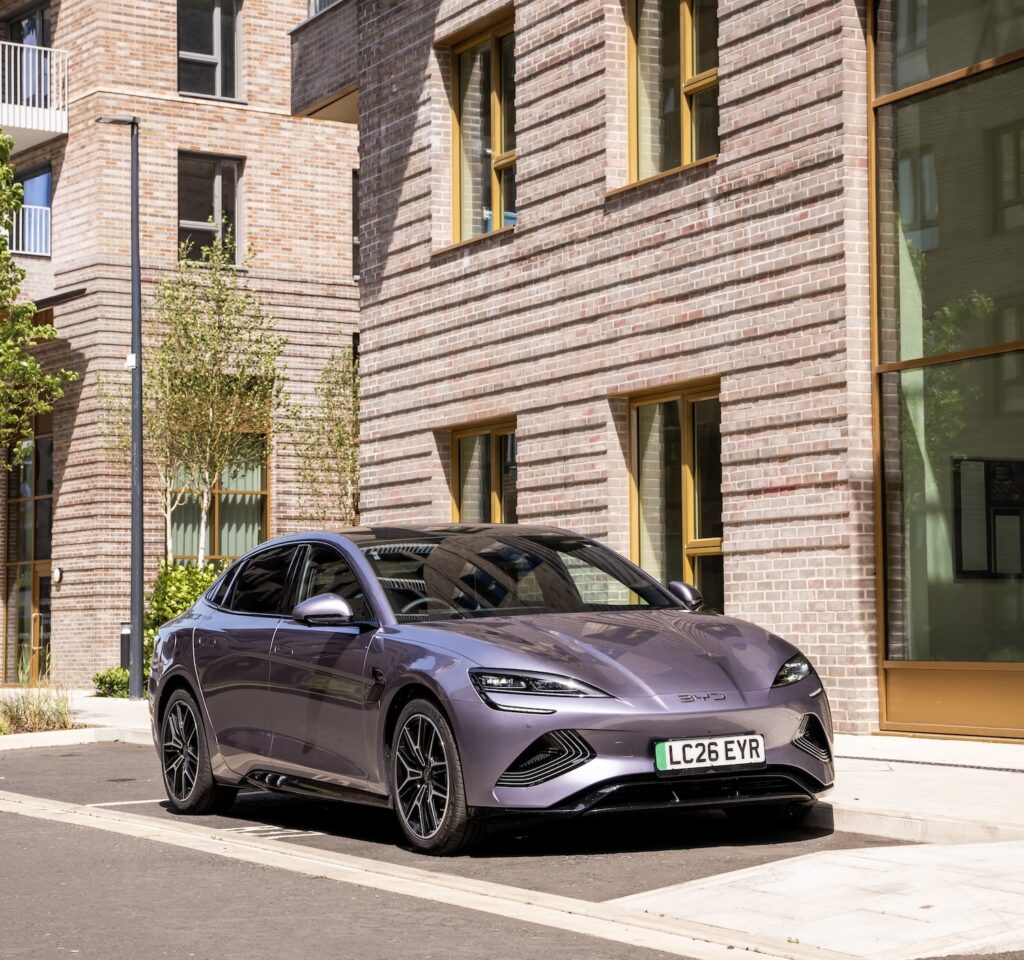
While BYD’s entry-level Seagull model pricing starts from around 69,900 yuan (c. £8,000) in China, the company also engineered the YANGWANG, the world’s fastest production car, and is currently rolling out five-minute fast-charging technology for a 400-kilometre range.
“What’s impressive about BYD in terms of sophistication is that it does its own chips, its own motors and its own batteries. That is very rare in the automotive world,” Burns said. “I’d go as far to say that my experience of Chinese EVs made me very worried about the future of the European mass auto market and how it would respond in the long run.”
Supporting the EV boom is battery maker CATL, which supplied nearly 40% of the world’s EV battery market last year and is rapidly expanding into grid-scale stationary storage. Beyond its manufacturing sophistication and dominance, Slater praised the firm’s cultural agility.
Slater said: “I think there’s something in there about the culture, about being prepared to walk away from what worked last year if you think there’s a better solution this year; to make sure you’re progressing all the different technologies, so you’re in a position to pick the winner.
“And if you’re really going to get at the competitive advantage of this business, despite the amazing manufacturing and the huge scale, I think it’s that technological understanding and making the right decisions that have been the absolute core of its position today.”
In artificial intelligence, China is taking a more practical route than Silicon Valley, where firms are racing to build frontier models and artificial general intelligence (AGI). “In China, you can probably see that most of the players run open-source models,” Lin said. “I think the reason for doing that is that China wants to bring down the cost of AI adoption. They want AI to be applied in different industries, not only in the digital world. They want AI to be in the factory, in the school – I mean, even in the public system, in the whole society.”
This extends to “physical AI” via holdings like autonomous-driving chip leader Horizon Robotics, as well as Scottish Mortgage’s largest Chinese holding, ByteDance. “It has its own model and the most powerful distribution platform both in China and globally,” Lin said of the TikTok owner. “ByteDance still remains the fastest-growing company in China.”
Observing Chinese innovation – from Meituan delivering iced lattes by drone to tourists on the Great Wall, to social commerce platforms like RedNote – helps the managers anticipate shifts in Western markets.
“These days, I think you look at what’s happening in China to get an idea of where business models might go in the rest of the world,” Slater said. “I don’t think there’s a western commerce market that you can analyse without understanding the effect of Temu or SHEIN and these business models which have been created in China, then brought to these markets and completely changed the dynamics in them.”
Lin noted that the era of neatly comparing Chinese firms to US peers as “China’s Google” or “China’s Uber” is over – especially with the West now trying to copy TikTok. The real danger for global investors is underestimating China’s industrial influence.
Lin concluded: “So I think the key point here is that understanding China is not only about finding investment opportunities; it’s actually about trying to understand where some very interesting, important industries are heading in the next few years.”
Enjoyed this story?